FranchiseHow to Buy a Franchise in 2026: Costs, Steps, Financing and Country Rules
How to buy a franchise in 2026: the 10 steps, real costs, financing options and disclosure rules in the US, China, UK, Australia, the Gulf and more.
Market intelligence/Western Europe/Report available
United Kingdom EV Service Centre Market Entry
Decision-grade assessment of the UK electric-vehicle aftersales market and the case for an EVS specialist service-centre and franchise pilot.
Plug-in cars
2.82m
Zero-emission cars: 1.74m
UK plug-in and zero-emission car stock at end-2025.
BEV/ZEV cars
473k
PHEV cars: 225k
2025 new-car demand.
Public chargers
119k
50kW+ chargers: 27k
Public charging network at 1 April 2026.
Verdict
Conditional go
Pilot hub: Birmingham-Coventry
EVS entry posture.
company-controlled Birmingham-Coventry validation hub, no-go for an immediate national franchise sale
01/The verdict in full
Verdict: conditional go for a staged, company-controlled Birmingham-Coventry validation hub; no-go for an immediate national franchise sale. The UK combines a 2.82 million plug-in car parc at end-2025, 473,226 new zero-emission cars in 2025, fast used-BEV growth, an ageing wider car parc and a well-established independent-garage culture. The demand case is strong; the constraint is proving lawful data/tool access, high-voltage competence and premium unit economics before scaling.
Recommended wedge: multi-brand diagnostics, battery state-of-health and thermal-system work, HV isolation/component replacement, charging faults, tyres/brakes/suspension, ADAS-partner workflows, used-EV inspections and fleet uptime. Lead with Tesla, BMW i, Audi e-tron, Mercedes-EQ, Porsche Taycan, Kia/Hyundai, Volkswagen Group, Nissan, MG/BYD and the fast-growing Chinese-brand parc.
Location strategy: operate the technical hub in Birmingham-Coventry for national motorway reach, automotive labour and lower occupancy cost than London; build London/Thames Valley demand through collection-delivery, mobile triage and dealer/fleet referral partners.
Investment stance: stage capital against a 100-job paid pilot, two contracted fleet/dealer channels, verified diagnostic coverage for at least 80% of the target parc and a credible route above £1.57 million annual break-even revenue for the illustrative six-bay centre.

02
The UK registered 473,226 new zero-emission cars in 2025, up 24% year on year and equal to 22.8% of new road-using car registrations under the official DfT definition. SMMT's market series reports 473,348 BEVs, 225,000 PHEVs and 2.021 million total new cars, placing BEV share at 23.4% and combined plug-in share at 34.5%. The small count differences reflect dataset timing and classification; the report does not blend them.
03
Zapmap, using SMMT registration data, reports 2,817,073 plug-in cars at end-2025, equal to 8.2% of the car parc. Official DfT zero-emission stock is narrower: 1.737 million zero-emission cars at end-2025 because PHEVs are excluded. EVS uses the broader plug-in figure for service-pool sizing and keeps the official ZEV stock as the auditable BEV/FCEV anchor.
04
The plug-in parc reached 2,157,360 vehicles at end-2024, including 1,334,246 BEVs. By end-2025, plug-in cars reached 2.817 million. Used-BEV transactions then rose 45.7% in 2025 to 274,815, while used PHEV transactions reached 88,032. This creates a growing cohort of second owners who are more price-sensitive and less tied to OEM service networks.
05
An SMMT long-term parc outlook estimated 9.3 million plug-in cars in 2030, including about 6.9 million BEVs. EVS treats 9.3 million as the base planning anchor and tests cautious and high cases of 7.0 million and 11.0 million. These are planning scenarios, not a claim that policy or demand will follow a single path.
06In the full report
At 1 April 2026 the UK had 119,080 public EV chargers, including 27,372 rated 50kW or above. At 1 January 2026, the comparable official release counted 87,796 charging devices and 116,052 charger/connectors, demonstrating why device and connector definitions must be kept separate. London has unusually high total provision per capita but relatively low rapid provision because its network is dominated by on-street units.
This section is in the full report.
07
SMMT counted 42.55 million vehicles and 36.68 million cars in use in 2025. The average car was 9.7 years old and 45.7% of cars were over 10 years old. EVs themselves are younger, but the established habit of maintaining older cars through independents is favourable once electric platforms leave warranty.
08
The sourced base is 2,817,073 plug-in cars at end-2025. EVS assumptions are: 0.72 relevant specialist jobs per plug-in car per year; £520 average revenue per job; 38% currently out of warranty or independently addressable; and 30% of that pool within priority regions and segments. The resulting TAM, eligible pool, SAM and pilot SOM are planning envelopes, not purchased market-revenue statistics.
09
10
Tesla Model Y led 2025 zero-emission registrations at 24,315, followed by Model 3 at 21,209 and BMW iX at 16,069 in the DfT model series. SMMT also identifies BYD Seal U and Jaecoo 7 among the leading electrified models. Launch capability should cover Tesla; BMW/MINI; Audi/VW/Skoda/Cupra; Mercedes; Porsche; Kia/Hyundai; Nissan/Renault; MG; and selected BYD/Jaecoo/Omoda platforms, with a published unsupported-function register.
11In the full report
OEM dealer groups control warranty, software, parts and goodwill. Tesla combines service centres, mobile service and collision partners. HEVRA supports a vetted network of more than 200 independent garages, demonstrating both demand and credible independent competition. Cleevely EV combines workshop and mobile servicing, while national fast-fit groups compete on tyres, brakes and routine work. EVS must differentiate through multi-brand HV depth, battery evidence, premium communication, fleet SLAs and auditable quality—not generic servicing.
This section is in the full report.
12In the full report
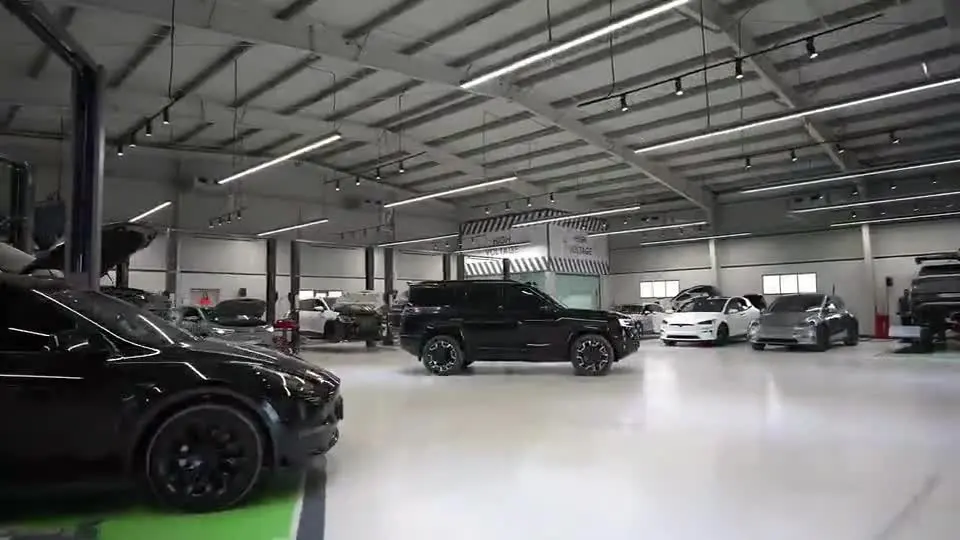
1. Birmingham-Coventry: primary technical hub. Central motorway access, automotive supply-chain depth and a more manageable cost base support a six-bay validation centre.
This section is in the full report.
13In the full report
Eligible new zero-emission cars priced at or below £37,000 can receive a point-of-sale Electric Car Grant of £1,500 or £3,750 depending on sustainability band and model eligibility. The grant supports fleet growth but is model-specific; EVS should never model all EV sales as subsidised.
This section is in the full report.
14In the full report
Zero-emission company cars carry a 3% Benefit-in-Kind rate in 2025/26, rising to 4% in 2026/27, 5% in 2027/28, 7% in 2028/29 and 9% in 2029/30. From April 2025, EVs also became liable for Vehicle Excise Duty; the standard annual rate shown in current guidance is £200 after the first year for newly registered zero-emission cars. A mileage-based eVED is planned from April 2028, adding a policy-risk factor to demand forecasts.
This section is in the full report.
15In the full report
A workshop can potentially use the £1 million Annual Investment Allowance for qualifying plant and machinery; companies may use 100% full expensing for eligible main-rate equipment. Separate 100% first-year allowances for qualifying zero-emission cars and EV chargepoints are extended to 31 March 2027 for Corporation Tax. The Workplace Charging Scheme offers up to £500 per eligible socket through 31 March 2027. Obtain UK tax advice before assuming eligibility.
This section is in the full report.
16In the full report
The HSE treats electric and hybrid vehicles as introducing additional workplace hazards. Employers must assess risk, control access to HV systems, provide appropriate training and equipment, isolate safely and plan for damaged or energised vehicles. The Electricity at Work framework is risk- and competence-based; EVS should require IMI Level 3/4-equivalent competence for defined tasks even where no single statutory 'EV mechanic licence' exists.
This section is in the full report.
17In the full report
IMI reported 71,942 EV-qualified technicians in Q3 2025, about 26% of the UK technician workforce, and projected demand could exceed supply by more than 44,000 by 2035. The National Careers Service gives a broad £22,000 starter to £42,000 experienced mechanic range; EVS should budget above generic benchmarks for diagnostic/HV leads and validate with local recruiter quotes.
This section is in the full report.
18
A centre offering MOT tests must be authorised by DVSA, appoint an approved business manager and testers, meet premises requirements and use approved/calibrated connected equipment. EVS can initially partner with a nearby MOT station to avoid delaying launch, then add in-house testing only when utilisation supports the bay and compliance burden.
19In the full report
Hazardous waste movements require consignment notes and duty-of-care controls. Removed or damaged lithium-ion packs need segregated, secure storage, fire planning and transfer to appropriately authorised carriers and facilities. Waste regulation is devolved: England, Wales, Scotland and Northern Ireland have different regulators and procedures, so a UK-wide franchise manual needs nation-specific annexes.
This section is in the full report.
20
Technicians recovering refrigerant from vehicle climate systems must hold the required F-gas qualification. Because heat pumps and thermal management are central to EV range and battery health, qualified climate-system capability should be part of launch, not an afterthought.
21In the full report
A UK private limited company pays Corporation Tax on profits and must register for VAT once taxable turnover exceeds the current £90,000 threshold; the standard VAT rate is 20%. An overseas company opening a UK establishment must register with Companies House, but a locally incorporated operating subsidiary is generally cleaner for employment, leases, insurance, VAT and future franchising. Legal and tax advice is required.
This section is in the full report.
22In the full report
The UK currently has no dedicated franchise statute; contract, competition, intellectual-property, employment and consumer law govern the relationship, while the BFA Code provides voluntary ethical standards. However, a February 2026 parliamentary committee recommended reviewing the landscape and considering a statutory code and independent enforcement. EVS should build disclosure, earnings-claim substantiation, fair renewal/termination and franchisee-support controls to a higher standard now.
This section is in the full report.
23In the full report
Launch: multi-brand diagnostic/root-cause reports; battery SOH and thermal diagnostics; HV isolation and component replacement; on-board charger/DC-DC/charge-port faults; heat-pump and A/C work; tyres, brakes, suspension and alignment; 12V systems; used-EV and collision inspections; software-update coordination where lawful; fleet preventive maintenance; collection-delivery and mobile triage.
This section is in the full report.
24In the full report
Create a UK operating company or tightly controlled joint venture for the first hub. EVS owns brand, SOPs, diagnostic policy, training, customer journey, warranty, data and audits. Use approved national partners for recovery, battery waste, ADAS, body repair and specialist remanufacture. Franchise only after at least 12 months of audited centre data, a documented disclosure pack, validated territory economics and a UK-specific operating manual with devolved compliance annexes.
This section is in the full report.
25In the full report
The illustrative six-bay model excludes VAT, financing, tax, land purchase and franchisor royalties. The base case assumes 300 productive days, 1.7 jobs per bay-day, a £520 average ticket, 54% contribution margin and £850,000 fixed operating cost. It yields £1.591 million revenue and approximately £9,000 EBIT—essentially break-even. Break-even revenue is about £1.57 million. The centre therefore needs diagnostic/battery mix, fleet utilisation and disciplined parts procurement; commodity work alone is insufficient.
This section is in the full report.
26In the full report
This section is in the full report.
27In the full report
Days 1-30 — prove access and demand: retain UK automotive/franchise counsel; shortlist three Birmingham-Coventry sites or host workshops; test tooling and parts on 12 priority platforms; obtain insurance and battery-waste proposals; interview 20 fleet, used-dealer and insurer buyers.
This section is in the full report.
28In the full report
Proceed only if: (1) lawful diagnostic/service coverage reaches at least 80% of the target-platform parc; (2) insurer, HV, fire, waste and site compliance are documented; (3) 100 paid jobs produce at least £520 average revenue; (4) contribution margin is at least 54%; (5) first-time-fix is at least 85% and comeback below 5%; (6) two fleet/dealer contracts cover at least 25% of base utilisation; (7) mature-year base revenue can exceed £1.57 million; and (8) the company/franchise structure receives written UK legal and tax clearance. Pause if a safety/legal gate fails or if a realistic site cannot reach £1.8 million revenue with at least 8% EBIT margin by month 18.
This section is in the full report.
29
Research prioritised DfT/DVLA, GOV.UK, HSE, HMRC, Parliament, SMMT, IMI and company primary sources accessed on 6 August 2026. DfT zero-emission vehicles exclude PHEVs; Zapmap/SMMT plug-in cars include BEVs and PHEVs. Charger and charging-device metrics also differ. These definitions are displayed separately. TAM/SAM/SOM and pilot economics are EVS assumptions with calculations exposed. City-level parc, workshop rent, fit-out, diagnostic subscription prices, technician pay, insurance and willingness-to-pay require local quotations and paid field validation before investment.
Method / Sources and confidence
Registrations, charging and legal requirements are read from primary sources. Where no official dataset exists, the model and its assumptions are published instead of a single unexplained number. This report is a dated snapshot: August 2026.
Reports are commercial research, not legal, tax or investment advice.
The complete assessment — competitive matrix, location shortlist, incentive and regulatory detail, pilot-centre economics and the 90-day entry plan. Sent straight to your inbox.
FranchiseHow to buy a franchise in 2026: the 10 steps, real costs, financing options and disclosure rules in the US, China, UK, Australia, the Gulf and more.
Market IntelligenceChina has 4.68 million of the world's 6.97 million public EV chargers. See 25 countries ranked by chargers, fast chargers and EVs per charger for 2026.
FranchiseOne in four new cars sold worldwide in 2025 was electric. What that means for an auto repair franchise, and how to judge an EV service franchise in 2026.
04 / Not in your country yet?
Tell us your territory. We'll send the market research alongside the franchise pack and connect you with the team behind every EVS centre.